What You'll Learn
- Which public-sector banks run home loan schemes for government employees, and what they give, as checked on 26 October 2026
- How the House Building Advance (HBA) at 7.10% compares with a bank loan
- Whether you can combine HBA with a bank home loan
- A worked example for a central government officer buying an ₹80 lakh flat
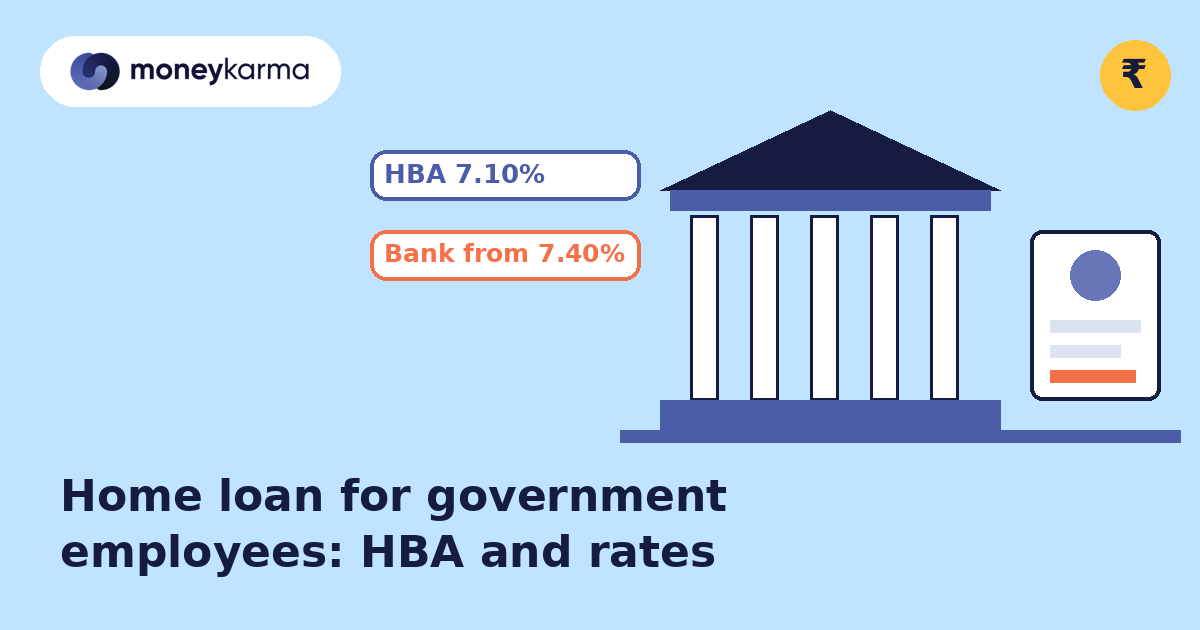
The best home loan for a government employee is often two loans: the House Building Advance from your employer at 7.10% simple interest, plus a bank home loan for the rest. Among bank loans, public-sector banks' schemes for government staff mostly save you the processing fee and protect your rate if your credit score is average. On lenders' own pages checked on 26 October 2026, one bank's government scheme charged 7.50% at any credit score, against 8.05% for other borrowers scoring 700 to 749. This guide comes from MoneyKarma, India's home loan platform with 90+ lenders. Not a lender.
Key takeaway: If you are a central government employee, apply for HBA first. Up to ₹25 lakh at 7.10% simple interest costs about ₹13.2 lakh in interest, against about ₹23.0 lakh on a ₹25 lakh bank loan at 7.40% over 20 years.
Do government employees get a lower home loan interest rate?
Sometimes, and it helps most if your credit score is average. Here is what public-sector banks' own pages showed on 26 October 2026. We don't name lenders. All are floating rates linked to the RBI repo rate, which is 5.50% after the 7 October 2026 increase.
| Lender type | Rate for government staff | Rate for others | What else you get |
|---|---|---|---|
| Public-sector bank A | 7.50% at any credit score (loan-to-value up to 80%) | 7.45% at 800+ (loans above ₹30 lakh), 7.50% at 750+, 8.05% at 700 to 749, 9.25% at 600 to 699 | Processing and documentation fees waived |
| Public-sector bank B | 7.40% at a score of 750 or more | 7.60% for salaried at 750 to 799 | Same 7.40% as its 825+ rate |
| Public-sector bank C | Card rate, with a small concession if your salary is with the bank | 7.50% onwards | Processing fee waived; repay up to age 75 instead of 70 |
| Public-sector bank D | No separate rate published | Card rate by loan size and credit score | Processing fee waived for government staff (out-of-pocket costs of ₹5,000 plus GST still apply) |
The lowest home loan rate open to any borrower that we found on 26 October 2026 was 7.25%, at a public-sector bank, for salaried borrowers with a credit score of 800 or more. So if your score is very high, a government scheme may not beat the best general offer. You can compare home loan interest rates across lenders on MoneyKarma.
What is the rate protection worth?
On a ₹50 lakh loan over 20 years, 7.50% instead of 8.05% lowers the EMI from ₹41,978 to ₹40,280. That is ₹1,698 a month, or about ₹4.08 lakh over the full term. At public-sector bank B, 7.40% instead of 7.60% saves ₹611 a month on the same loan.
What is the House Building Advance and who can get it?
HBA is a loan from the central government to its own employees to build or buy a house or flat, or to expand one. The Ministry of Housing and Urban Affairs set the rate for 2026-27 at 7.10% a year, from 1 April 2026 to 31 March 2027. It carries simple interest, not the compounding of a bank EMI.
Under the HBA Rules as compiled by the ministry:
- For a new house or flat you can get 34 months' basic pay, up to ₹25 lakh, or the cost of the house, or what you can repay, whichever is lowest.
- The house you buy or build should cost no more than 139 times your basic pay, up to ₹1 crore.
- You repay the principal first, in up to 180 monthly instalments, and then the interest in up to 60 instalments.
- Only one HBA is allowed in your whole service, and the house must be insured against fire, flood and lightning.
State governments run their own house building advance schemes with different limits and rates, so check your state's rules if you are a state employee.
Can you combine HBA with a bank home loan?
Yes. The ministry's FAQs say you can take a bank or housing finance loan for the balance cost, with HBA as the first charge on the property and the bank loan as a second charge. The total from all sources can't cross the HBA cost ceiling. You need a no-objection certificate for the second charge, and you should confirm the bank will lend on a second charge before you apply. HBA can also be used to repay an existing bank home loan, subject to the rules.
How much home loan can a government employee get?
Banks size the loan on your take-home salary and existing EMIs, and then cap it by the property's value. RBI limits housing loans to 90% of value up to ₹30 lakh, 80% above ₹30 lakh to ₹75 lakh and 75% above ₹75 lakh. A government job helps because banks treat the income as stable, and some allow the EMI to be deducted from salary at source, known as check-off, which can bring a concession. MoneyKarma's home loan eligibility guide explains how lenders work out the amount.
Tenure matters too. Public-sector bank C allows repayment up to age 75 under its scheme for government staff, against 70 for its regular home loan. For a 45-year-old buyer that can mean a longer loan and a lower EMI, paid partly from pension.
A worked example: Kavita buys an ₹80 lakh flat in Noida
Kavita, 36, is a central government officer with a basic pay of ₹80,000 and a credit score of 760. She is buying an ₹80 lakh flat. These are MoneyKarma calculations using the standard reducing-balance EMI formula and the rates above.
| Step | Figure |
|---|---|
| HBA limit: 34 months' basic pay, capped | ₹25 lakh |
| Cost ceiling: 139 times basic pay, capped | ₹1 crore, so the flat qualifies |
| Total borrowing, assumed at 80% of value | ₹64 lakh |
| Bank loan for the balance | ₹39 lakh at 7.40%, 20 years, EMI ₹31,180 |
| HBA repayment | ₹13,889 a month for 15 years, then about ₹22,064 a month for 5 years |
| HBA interest over the life | About ₹13.2 lakh |
| Same ₹25 lakh from a bank at 7.40% | Interest about ₹23.0 lakh |
HBA saves Kavita about ₹9.7 lakh in interest on the first ₹25 lakh. On the bank side, a waived processing fee is worth up to ₹15,000 plus GST on a ₹39 lakh loan at public-sector bank D, which otherwise charges a fee of ₹8,500 to ₹15,000 on loans up to ₹50 lakh.
What should government employees check before applying?
- Whether the scheme needs your salary account with that bank, and whether check-off is required for the concession.
- Whether the concession applies at your credit score. At public-sector bank A the government rate equals the 750+ rate, so it helps most below 750.
- The full cost: legal, valuation and stamp duty on the mortgage still apply even when the processing fee is waived. MoneyKarma's home loan charges and eligibility page lists them.
- For HBA, your department's processing time. If it is slow, you can take the bank loan first and use HBA later to repay it, which the rules allow.