What You'll Learn
- How much home loan you can get on an ₹80,000, ₹1 lakh or ₹1.5 lakh salary in Delhi, at rates checked on 30 October 2026
- Delhi's stamp duty and registration charges in rupees, and why a woman buyer pays 2% less
- The cash a ₹60 lakh or ₹1 crore Delhi home needs on top of the loan
- What Delhi NCR's Q3 2026 housing data says about prices and sales
On an ₹80,000 monthly salary and a credit score of 750, you can expect a home loan of about ₹49.7 lakh in Delhi over 20 years, if your lender lets half your pay go to EMIs and you have no other loans. On top of the down payment, you pay 7% of the property value in stamp duty and registration if the buyer is a man, or 5% if she is a woman. Home loan rates don't change by city: the lowest we found on lenders' own pages on 30 October 2026 was 7.25% at a public-sector bank. This guide comes from MoneyKarma, India's home loan platform with 90+ lenders. Not a lender.
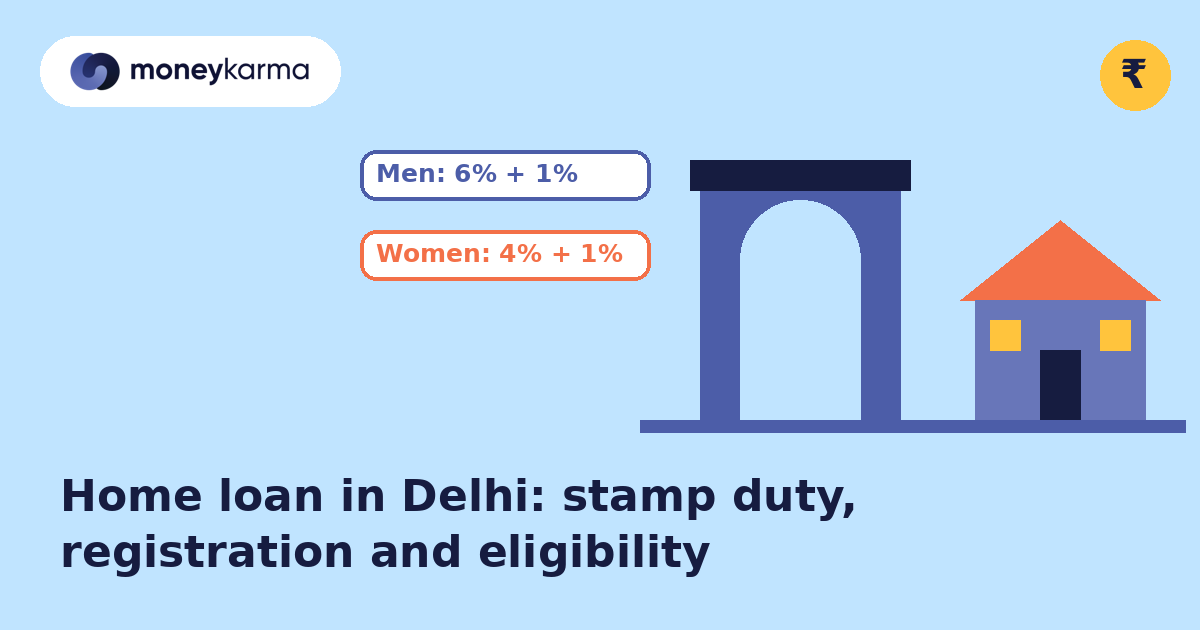
Key takeaway: Delhi charges men 6% stamp duty and women 4%, plus a 1% registration fee for both. On a ₹60 lakh flat, registering it in a woman's name saves ₹1.2 lakh, and no lender will finance these charges for you.
How much home loan can I get on my salary in Delhi?
Lenders apply two limits and give you the lower one: the EMI your income can carry, and the share of the property's value they may fund.
The first depends on FOIR, the share of monthly income that can go to all EMIs together. Each lender sets its own; the table uses 50% as an illustration, with no other EMIs. These are MoneyKarma calculations using the standard reducing-balance EMI formula.
| Monthly salary | EMI at 50% FOIR | Loan at 7.50%, 20 years | Loan at 7.50%, 30 years | Loan at 8.00%, 20 years |
|---|---|---|---|---|
| ₹80,000 | ₹40,000 | ₹49.7 lakh | ₹57.2 lakh | ₹47.8 lakh |
| ₹1 lakh | ₹50,000 | ₹62.1 lakh | ₹71.5 lakh | ₹59.8 lakh |
| ₹1.5 lakh | ₹75,000 | ₹93.1 lakh | ₹107.3 lakh | ₹89.7 lakh |
7.50% is what a 750 to 799 credit score gets a salaried borrower at the public-sector bank with the lowest rates we found; 800 or more gets 7.25%, and 700 to 724 gets 8.00%.
You can check your own numbers on MoneyKarma's home loan eligibility page.
What can a couple earning ₹1.5 lakh together borrow?
About ₹93 lakh over 20 years at 7.50%, if neither has other EMIs. A co-applicant raises the income limit, not the property-value cap.
How much of a Delhi property's value will a bank fund?
RBI caps the loan as a share of the home's value, based on the loan size:
| Loan amount | Maximum loan as a share of property value |
|---|---|
| Up to ₹30 lakh | 90% |
| Above ₹30 lakh to ₹75 lakh | 80% |
| Above ₹75 lakh | 75% |
These caps come from RBI's housing loan rules for banks, updated 1 October 2026, and apply in every city. Stamp duty and registration are left out of the value, except for homes up to ₹10 lakh, so you pay them yourself.
What are stamp duty and registration charges in Delhi?
The Delhi government's Revenue Department lists these rates for a sale deed, conveyance deed or gift deed:
- Stamp duty: 6% for a male buyer and 4% for a female buyer, on the deal value or the area's circle rate, whichever is higher
- Registration fee: 1% of the deal value or circle-rate value, whichever is higher, plus a ₹100 pasting fee
Here is what that means in rupees, using the price as the value:
| Charge | On a ₹60 lakh home | On a ₹1 crore home |
|---|---|---|
| Stamp duty, male buyer (6%) | ₹3,60,000 | ₹6,00,000 |
| Stamp duty, female buyer (4%) | ₹2,40,000 | ₹4,00,000 |
| Registration fee (1% plus ₹100) | ₹60,100 | ₹1,00,100 |
| Total, male buyer | ₹4,20,100 | ₹7,00,100 |
| Total, female buyer | ₹3,00,100 | ₹5,00,100 |
If your price is below the area's circle rate, duty is charged on the circle-rate value. The department's page lists only the male and female rates for these deeds, so for a home bought jointly by a man and a woman, ask the sub-registrar's office how the duty will be worked out before you budget.
Gurugram and Faridabad (Haryana) and Noida and Ghaziabad (Uttar Pradesh) set their own stamp duty.
What would Ankit need in cash for a ₹60 lakh flat?
Ankit, 31, a salaried analyst on ₹80,000 a month with a 750 credit score and no other loans, is buying a ready-to-move ₹60 lakh flat in Dwarka.
| Item | Amount |
|---|---|
| Home loan (80% of value) | ₹48 lakh |
| Down payment | ₹12 lakh |
| Stamp duty and registration (male buyer, 7% plus ₹100) | ₹4,20,100 |
| Cash needed before interiors and brokerage | ₹16,20,100 |
| EMI on ₹48 lakh at 7.50%, 20 years | ₹38,668 |
His EMI takes 48.3% of his salary, just inside our illustrative 50% FOIR. Over 30 years it drops to ₹33,562, at the cost of far more interest. If his mother were the buyer on the deed, the cash needed would fall to ₹15,00,100, because she would pay 4% stamp duty instead of 6%. Lenders generally want every owner on the loan, so check this with yours first.
A score of 800 or more would get him 7.25% at the same bank: ₹730 less a month, ₹1.75 lakh less over 20 years.
And for a ₹1 crore home?
The 75% cap limits the loan to ₹75 lakh, with an EMI of ₹60,419 at 7.50% over 20 years. Cash needed, with the ₹25 lakh down payment and charges, is ₹32,00,100 for a male buyer and ₹30,00,100 for a female buyer.
What is happening to Delhi NCR home prices?
Prices in Delhi are rising even as sales across NCR fall. Knight Frank's India residential report for July to September 2026 shows:
- NCR home sales of 10,712 units in Q3 2026, down 17% from a year earlier
- NCR launches of 10,071 units, down 5%
- Weighted average prices up 17% year on year in Delhi, with no change from the previous quarter
- Price growth of 7% in Noida, 4% in Gurugram, 14% in Ghaziabad and 17% in Faridabad over the year
Higher prices raise both the down payment and the stamp duty, since each is a share of the price.
Do Delhi lenders charge different home loan rates?
No. Lenders price home loans the same way in every city: a benchmark linked to the RBI repo rate of 5.50%, plus a spread for your credit score, income type and loan size. On 30 October 2026, starting rates at four public-sector banks were 7.25%, 7.40%, 7.45% and 7.50%. Two large private banks started at 8.00% and 8.75%. Compare spreads and fees, not a "Delhi rate". See today's home loan interest rates on moneykarma.com, and the full list of home loan charges and eligibility rules.
Relocating with a costlier existing loan? A home loan balance transfer can move it.
Which lenders disburse fastest in Delhi?
Speed depends more on your file than the lender. Complete papers (KYC, salary slips, bank statements, Form 16, property chain documents) and a project the lender has already approved shorten the legal and technical checks.