What You'll Learn
- Plot loan interest rates at banks and housing finance companies, from lenders' own pages on 23 October 2026
- Who is eligible for a land purchase loan, and which plots lenders won't touch
- How much you can borrow, and why a plot loan costs more than a home loan
- The build-by deadline, and what happens to your rate if you miss it
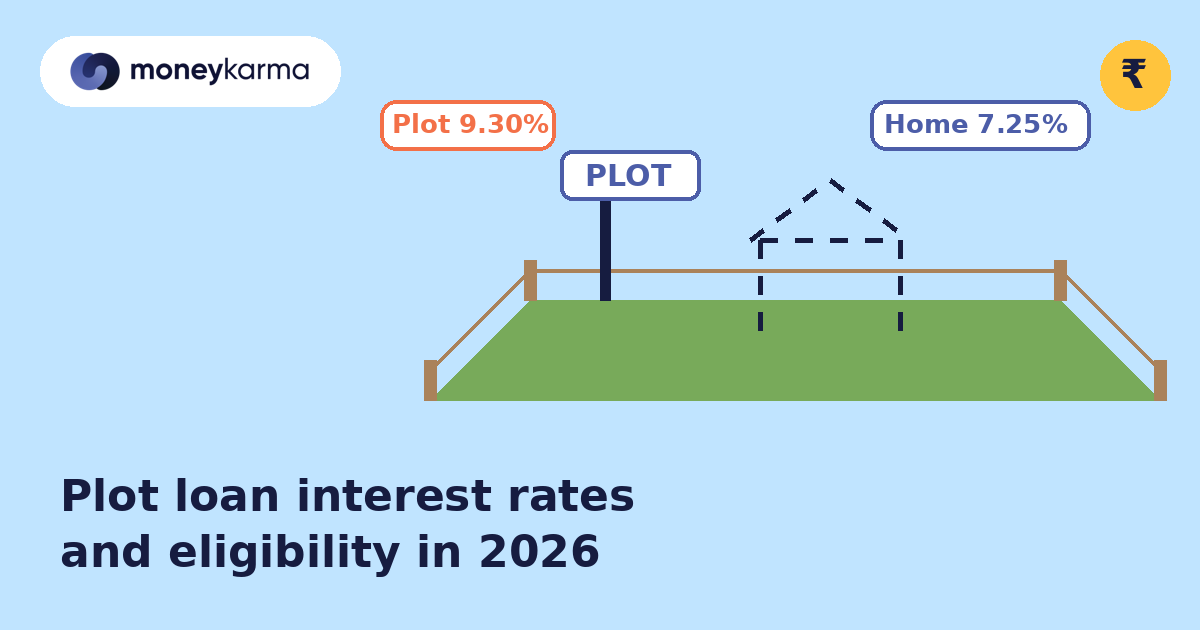
Plot loan interest rates start well above home loan rates. On lenders' own pages checked on 23 October 2026, public-sector banks charge 9.30% to 10.50% for a plot loan to borrowers with good credit scores, against a lowest home loan rate of 7.25%. A private bank's plot loan card runs from 8.00% to 13.45%. Most lenders fund 75% to 80% of the plot's value, cap the tenure at 10 to 20 years and expect a house within four or five years. This guide comes from MoneyKarma, India's home loan platform with 90+ lenders. Not a lender.
Key takeaway: A plot loan at a public-sector bank costs about 2 to 3 percentage points more than a home loan, and at one bank the rate rises to 11.90% or more if the house isn't built within five years. Compare the build-by deadline as closely as the rate.
What are plot loan interest rates today?
Figures are from each lender's own rate page, checked on 23 October 2026, unless noted. Lenders aren't named. All are floating rates tied to the RBI repo rate, now 5.50% after the 7 October 2026 increase.
| Lender type | Plot loan rate | Benchmark | Maximum tenure |
|---|---|---|---|
| Public-sector bank A | 9.30% to 10.35%, by credit risk grade | RLLR 8.25% from 9 October 2026 | 10 years |
| Public-sector bank B | 9.50% (score 800+) to 10.50% (680 to 699) | RLLR 8.35% from 8 October 2026 | 15 years or age 70 |
| Private bank | 8.00% to 13.45% | Repo 5.50% + 2.50% to 7.95% | 15 years |
| Housing finance company | From 7.35% salaried, 7.50% self-employed (score 825+) | Lender's own prime rate | 15 years |
The housing finance company's figure is from its plot loan card as reported in mid-October 2026; its page didn't load for us on 23 October, so confirm it with the lender.
For comparison, the lowest home loan rate we found on 23 October 2026 was 7.25%, at a public-sector bank, for salaried borrowers with a credit score of 800 or more. You can check home loan interest rates across Indian banks on MoneyKarma.
Why is a plot loan dearer than a home loan?
A vacant plot is harder to value and sell than a finished flat, and the lender can't be sure you'll build. So it charges more and lends less.
Which is the best bank for a plot loan in India?
There's no single best bank. It depends on your credit score, how soon you'll build and how long you need to repay. Three things matter more than the headline rate:
- The deadline to build. One private bank wants the house finished within four years of disbursement; bank B allows five.
- The penalty if you don't build. Bank B's plot rate applies for five years; if the house isn't complete by then, it moves to a commercial rate of 11.90% to 12.50%.
- The tenure. A 10-year cap pushes the EMI up sharply.
Is a housing finance company better for a plot loan?
Sometimes. If you want the best NBFC for a plot loan, compare housing finance companies, a type of NBFC. The one we looked at starts below the public-sector banks, at 7.35% for salaried borrowers scoring 825 or more, and funds up to 75% over up to 15 years. Its rates climb as the score falls, so compare at your actual score.
Who is eligible for a land purchase loan in India?
For borrowers, the pages we checked on 23 October 2026 set these limits:
- Age: 21 to 60 at entry at bank B (co-applicant needed above 55); 18 to 70 at the private bank; loan closed by 65 at bank A.
- Income: bank A lends up to three times gross annual income; another private bank wants at least ₹30,000 a month.
- NRIs: accepted at bank B and the housing finance company.
Which plots qualify?
Lenders want a residential plot with clear title in an approved layout: plots allotted by development or town planning authorities, layouts approved by the state's statutory authority, or RERA-registered projects. Resale plots are usually fine if the title chain is clean.
Expect a no for agricultural land, unapproved layouts and land the bank can't enforce its mortgage on. Public-sector bank B says the plot must be SARFAESI compliant, so the bank can take possession if the loan goes bad. Get the lender's legal checklist before you pay the seller a token amount.
How much plot loan can you get?
You get the lower of a share of the plot's value and what your income can repay. Stamp duty and registration are on you.
| Lender type | Share of plot value funded |
|---|---|
| Public-sector bank A | Up to 75% of site cost or guideline value, whichever is lower |
| Public-sector bank B | Up to 75% (25% minimum margin), ₹10 lakh to ₹3 crore in cities |
| Private bank | 80% for loans up to ₹75 lakh, 75% above |
| Housing finance company | Up to 75% |
A worked example: ₹40 lakh plot in Hyderabad
Kavya, 34, a salaried software tester in Hyderabad with a credit score above 800, wants a ₹40 lakh plot in an approved layout and plans to build within four years. At 75% funding she borrows ₹30 lakh and pays ₹10 lakh herself, plus stamp duty and registration. These are MoneyKarma calculations using the standard reducing-balance EMI formula; the price and profile are illustrative.
| Option | Rate | Tenure | EMI | Total interest |
|---|---|---|---|---|
| Public-sector bank B plot loan | 9.50% | 15 years | ₹31,327 | ₹26.4 lakh |
| Public-sector bank A plot loan | 9.30% | 10 years | ₹38,492 | ₹16.2 lakh |
| Same ₹30 lakh at the lowest home loan rate | 7.25% | 15 years | ₹27,386 | ₹19.3 lakh |
Bank B's plot loan costs Kavya ₹3,941 a month more than a home loan of the same size. Bank A's 10-year cap puts her EMI about ₹7,200 above bank B's, though she pays less interest overall.
What if Kavya doesn't build within five years?
At bank B she'd owe about ₹24.2 lakh after five years. If the rate then moves to 11.90% for the last 10 years, her EMI rises from ₹31,327 to ₹34,594. Plan the build money before you buy the land.
Can you claim tax benefits on a plot loan?
Not while the land is empty. Under the Income-tax Act, 2025, the interest deduction in section 22 is for a house, and a vacant plot isn't one. Once the house is finished, interest paid before completion can be claimed in five equal yearly parts, within the ₹2 lakh yearly cap for a self-occupied home under the old regime. Ask a tax adviser how your plot loan interest is treated.
If you'll build soon, ask for a composite loan quote too. At one public-sector bank, a loan to buy a plot and build on it sits inside its regular home loan scheme, which starts at 7.25%.